

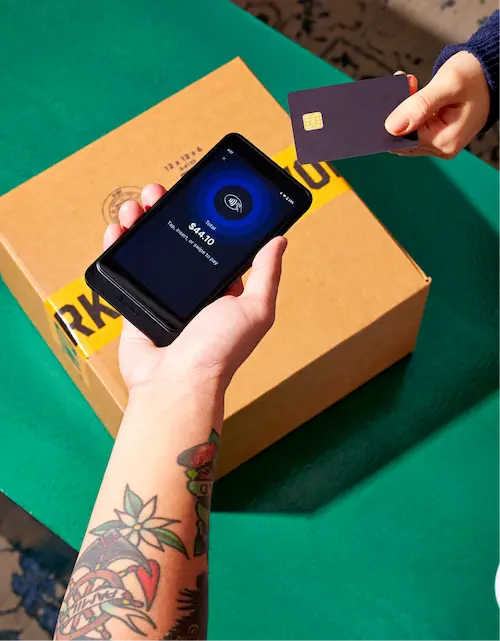


NFC mobile payments are contactless transactions in which a customer taps their smartphone, watch, or card to pay wirelessly, without swiping or inserting anything.
Visa reports that tap to pay is their cardholders’ default payment method, representing 79% of face-to-face transactions worldwide and 66% in the United States in the 2025 fiscal year. Most in-person Visa payments are now taps from an NFC-enabled card or smartphone, not swipes or inserts.
This guide covers what NFC mobile payments are, how secure they are, and how to start accepting them at your store.
What is an NFC payment?
A near-field communication (NFC) payment is a contactless transaction in which a card, phone, or watch sends payment data to a reader using a short-range wireless connection.
NFC is the wireless technology itself, contactless payment is the category of payment methods that NFC enables, and tap to pay is the specific action a customer takes by holding their card, phone, or watch near a reader to complete a transaction.
NFC technology powers two different payment methods:
- Credit and debit cards. Contactless credit and debit cards use NFC, a short-range form of radio frequency identification (RFID), to communicate with payment terminals.
- Mobile phones and smartwatches. Mobile wallet apps like Apple Wallet, Google Wallet, and Samsung Wallet use the device’s built-in NFC radio to communicate with NFC payment devices. Rather than transmitting the card’s actual number, the wallet sends a device-specific token paired with a one-time payment cryptogram generated for that single transaction.
With Shopify POS hardware, customers can tap to pay at the counter, on the sales floor, and on the go.
How do contactless payments work?
A contactless payment is a sequence of steps between the customer’s device and the payment terminal that takes place in seconds:
- The customer presents their tap-enabled card, phone, or watch. A phone or watch needs the customer to confirm with facial recognition (such as Apple’s Face ID), a fingerprint, or a passcode, or the tap won’t go through.
- The terminal and the card or device connect over NFC. NFC operates at 13.56 MHz with a typical range of four centimeters (1.5 inches) or less. If the card or device is held too far away, the reader won’t connect.
- The card or device sends encrypted transaction data. Cards and devices both add a one-time cryptogram, and phones and watches send a token in place of the card number. A cracked chip antenna on a card can block the connection and cause failed taps.
- The terminal forwards that data to the store’s payment processor. The terminal needs an active internet or cellular connection, or it can’t reach the processor.
- The processor routes the transaction to the card network and the customer’s bank for authorization. If the bank declines the transaction due to insufficient funds, a spending limit, or a security flag, the tap will not be accepted.
- The terminal confirms the sale within a couple of seconds. If a receipt or confirmation screen doesn’t appear, check the terminal display before asking the customer to tap again to avoid duplicate charges.
Cards that support tap payments carry a Contactless Indicator of four curved lines; terminals display a matching Contactless Symbol so customers know tap is a payment option.
How secure are NFC and contactless payments?
NFC and contactless payments combine several protections on top of a standard card transaction.
Tokenization replaces your customer’s card number
Mobile wallets rely on payment tokenization. Instead of transmitting the card’s 16-digit number, the wallet sends a device-specific token paired with a one-time cryptogram generated for that one purchase. Visa reports they had provisioned more than 16 billion tokens as of September 30, 2025.
If someone intercepts a token, it works only on the device it was issued to, and its cryptogram works only once. Because the card number never reaches the terminal, tokenized transactions shrink how much of a store’s environment falls under Payment Card Industry Data Security Standard (PCI DSS) requirements.
Why a tap beats a magnetic stripe swipe
A magnetic stripe stores the same static card data each time it’s swiped, so anyone who copies that data can reuse it later. An EMV (Europay, Mastercard, and Visa) chip, whether inserted or tapped, and a mobile wallet both generate a new one-time transaction security code for each purchase. Even if someone captures that code in transit, it won’t authorize a second transaction.
What this means for card skimming
Traditional skimmers copy the static data off a magnetic stripe to clone an active card. That doesn’t work against an EMV contactless transaction, because the one-time code a chip card or mobile wallet generates expires after a single use.
NFC and contactless payments render this specific fraud method useless, but they don’t eliminate fraud altogether. Fraud and unauthorized charges can still come from a lost phone, stolen card, or compromised account.
Mobile wallets add a second check
Mobile wallets such as Apple Wallet ask the customer to confirm with Face ID, a fingerprint, or a passcode before most taps go through. A thief can tap a stolen card up to the contactless limit, but a stolen phone still needs its owner’s biometrics or passcode.
How to accept NFC and contactless payments
Before your store can accept tap to pay, you need a payment processor or payment service provider account and a contactless-capable way to accept payments.
That doesn’t need to be a dedicated payment terminal. A compatible smartphone works too. In fiscal 2025, Visa reported that they passed 20 million Tap to Phone transacting devices, phones with an NFC radio, converted into acceptance terminals.
Any business that accepts cards, along with its processor, must meet the PCI DSS, the baseline security standard card networks require of anyone who touches cardholder data.
Once you have the right tools in place, follow these steps.
1. Set up Shopify Payments
Start by activating Shopify Payments in your store. Shopify’s card readers and tap to pay both run on Shopify Payments.
Availability varies by country, so first confirm that Shopify Payments supports in-person processing where your store operates. If Shopify Payments isn’t available in your country, you can take payments on an external provider’s terminal and record them in Shopify POS as a custom payment type instead.
2. Get the right hardware
Stores can accept contactless payments through one of three setups:
- A countertop terminal, such as Shopify POS Terminal, at a fixed checkout area
- A handheld reader, such as the Shopify Tap & Chip Reader, for the sales floor or events
- Tap to pay on a compatible iPhone or Android device in supported countries, no extra hardware required
The right fit depends on how and where you sell your products. If you regularly host store pop-ups, a handheld reader or compatible smartphone travels with you. A single brick-and-mortar store can keep a payment terminal at a fixed checkout counter.
Sukhmani Designs, a home and design retailer, uses tap to pay during in-home design consultations.
“I love that I can access Shopify POS anywhere and process payments right at clients’ homes without worrying about paying extra fees,” says Owner Sat Gurumukh Khalsa.
Accepting card-present transactions, instead of keying in a card number, saved Sukhmani Designs from the higher processing fees that come with off-site keyed entries and made things more convenient for their customers.
At high-volume events, a phone and a card reader can be enough.
“We’ve processed upward of 2,000 to 3,000 transactions a day at music festivals with a card reader and an iPhone,” says Curtis Ulrich, director of ecommerce at Aviator Nation.
3. Choose your payment options
A mobile wallet app, like Apple Wallet, Google Wallet, or Samsung Wallet, is the software on a customer’s phone or watch that stores their cards. Apple Pay, Google Pay, and Samsung Pay are the payment services those apps use when customers tap to pay.
Shopify card readers accept all three payment services, along with contactless cards, with no extra setup. If you also sell online, turn on Apple Pay and Google Pay in your Shopify admin so customers can use them at online checkout too.
4. Tell your customers
A terminal that accepts contactless payments will display the four curved lines of the Contactless Symbol. You can also place a sign near the reader to let customers know they can tap.
Why should you accept NFC and contactless payments?
NFC and contactless payments offer two advantages: convenience and speed.
Convenience
The share of US consumers making mobile payments at the point of sale more than doubled between 2021 and 2025, from 8.9% to 21.3%. Roughly 70% of those in-person mobile payments were tap to pay.
Fast checkout
According to S&P Global 451 Research, 53% of US consumers prefer contactless payments, rising to 65% among Gen Z. A contactless tap authorizes in seconds with a single gesture, unlike a chip insert.
Note that the speed only applies to authorization. Your store’s payment processor still settles the funds and deposits them into your bank account on its normal payout schedule.
What are the drawbacks of NFC and contactless payments?
NFC and contactless payments have three drawbacks to weigh when you’re setting up payment processing for your store: they require compatible equipment, they’re subject to transaction limits, and they’re only as secure as the customer’s device.
They require compatible equipment
You must have an NFC-equipped device to accept contactless payments. If you already have an established checkout counter in your store, this may mean investing in payment terminals equipped with the right kind of NFC radios.
However, you can use tap to pay on a compatible iPhone or Android device to avoid purchasing new equipment. Mastercard’s 2025 annual report says their Tap on Phone acceptance technology lets businesses accept contactless cards and mobile wallets directly from their own device “without any additional hardware required.”
Compatibility and regional or provider requirements still apply, even when using a smartphone to accept payments.
Transaction limits
Contactless spending limits vary by card network, card issuer, and country, so it’s difficult to plan around a specific cap. For example, Visa cards in the UK have a £100 limit, though the cap doesn’t apply to mobile wallets like Apple Pay and Google Pay.
Check each card network and issuer in your country to see whether you need to plan around lower contactless transaction limits.
It’s only as secure as the user’s device
If someone knows a phone’s passcode or has an unlocked watch, they can use whatever mobile wallet is set up on it. And if someone has set up Apple’s Express Mode, they can use eligible cards and passes, such as transit cards, without waking or authenticating the device.
To prevent this type of fraud, customers should lock their phones and watches with a passcode plus a fingerprint or facial recognition.
Tapping versus scanning a QR code
With QR code payment, a customer scans a QR code that takes them to a payment page where they manually approve a transaction with their banking or payment app. While you can still make this type of payment on a smartphone, it’s a different and more time-consuming process than holding a card or device near a reader.
Shopify treats QR-based local payment methods on Shopify POS as non-card-present (NCP) transactions, so online Shopify Payments rates apply instead of card-present rates.
Accept NFC payments for your business
Start accepting NFC payments in a few steps. First, confirm that Shopify Payments supports in-person payments in your store’s country.
Then choose your hardware: an NFC-equipped countertop terminal, handheld reader, or tap to pay setup on a compatible smartphone. From there, let customers know their payment options.
Read more
- How to Accept Credit Card Payments In-Store or Online
- Product Packaging Design- Get Your Brand Ahead At First Impression
- Understanding PSD2 and Strong Customer Authentication
- Packaging Inserts Ideas- 7 Ways to Increase Customer Loyalty
- Business Renters Insurance- A Guide for Business Owners
- Ecommerce Accounting for Small Business Owners
- How Recurring Payments Work for Small Business Owners
- From Realtor to Retailer- How Strategic Financing Helped One Entrepreneur Scale Quickly
- Electronic Payment- What Small Business Owners Should Know
- Business Owner’s Policy- Your Guide to Small Business Insurance
NFC mobile payments FAQ
Does my phone support NFC payment?
Your phone supports NFC payments if it has an NFC chip, which current iPhone, Samsung, and Google models include. Check your phone’s settings or the manufacturer’s specifications page to confirm NFC is available and turned on. A phone with NFC and a supported wallet can make tap payments.
Is it safe to pay with NFC?
Paying with NFC is safer than swiping a magnetic stripe. NFC payments use a one-time transaction code, and mobile wallets add tokenization, so the data a terminal receives can’t be used for another purchase. Mobile wallet payments also require the customer to authenticate the device before most transactions go through.
Is Apple Pay an NFC mobile payment?
Apple Pay is an NFC mobile payment service that uses an iPhone or Apple Watch’s built-in NFC radio to communicate with a payment terminal. It sends a device-specific token instead of the customer’s actual card number to complete a transaction.
Can I take NFC payments on my phone?
You can take NFC payments on your phone with Shopify POS, which supports tap to pay on compatible iPhone and Android devices in supported countries, using Shopify Payments. Download the Shopify POS app, add items to a cart, and your phone will become a payment terminal for in-person customers without an extra card reader.
How do I pay with NFC?
To pay with NFC, add a mobile wallet app, such as Apple Wallet, to your phone. Depending on your phone’s model, it may already come equipped with a compatible mobile wallet app.
Connect your mobile wallet to your credit or debit card, then confirm with facial recognition, a fingerprint, or a passcode, and hold your phone or watch near a payment terminal that displays the Contactless Symbol. A tap-enabled card works the same way. Hold it near the reader instead of inserting or swiping it.


